In today’s housing market, extended loan terms, stretching the 25-year agreement to 35 or 40 years, have become a practical reality for home buyers.
Dubbed ‘marathon mortgage’ these extended terms help borrowers manage their initial monthly cash flow amid high house prices and strict lender affordability checks.
Data from the Financial Conduct Authority (FCA) and Bank of England show 11% of new mortgage originations now exceed 35-year terms – almost a fourfold increase from pre-2022 levels. Meanwhile, 40% of all new mortgage lending now carries a term that extends past state pension age.
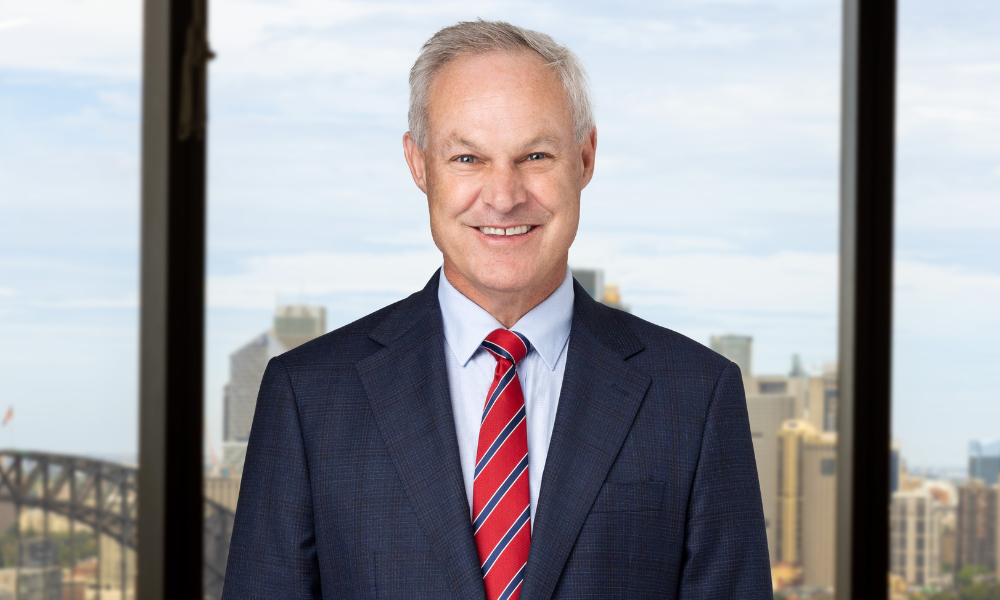
John Fraser-Tucker, head of mortgages at Mojo Mortgages, said: “While opting for a 35- or 40-year mortgage is an effective strategy to lower initial monthly repayments, it also shifts the timeline for mortgage repayment.
“For borrowers whose loan terms run into their 60s or 70s, understanding how mortgage renewals work as retirement approaches is crucial for ensuring smooth transitions between fixed terms.”
How do ‘marathon mortgages’ work over the long term?
Fraser-Tucker explained, to understand the mechanics of a ‘marathon mortgage’, it helps to weigh the short-term flexibility against the long-term structure.
In the short term, there is there is immediate monthly relief. Spreading a principal balance over 35 or 40 years instead of 25 can lower monthly repayments by roughly 15% to 25%, providing financial breathing room during high-cost years.
However, because initial payments are spread over a longer period, principal reduction occurs at a slower pace in the early years. On a £300,000 balance at a 4% interest rate, a 40-year term adds significant interest over the total life of the loan compared to a 25-year term if paid passively.
It’s not set in stone forever, though. A marathon mortgage is rarely static, Fraser-Tucker said. “Most borrowers refinance or adjust their terms multiple times over the course of the loan as their income, household needs, and career stages evolve,” he added.
What happens if your fixed rate deal ends near retirement?
One of the main concerns with ‘marathon mortgages’ is borrowers are more likely to be repaying the loan as they approach or hit retirement.
Fraser-Tucker said transitioning from earned employment income to fixed retirement income alters how lenders review a mortgage application.
“If your current fixed deal is coming to an end and your new term will run up to or past your planned retirement date, lenders evaluate three key factors,” he explained.
Here are some factors to consider ahead of retirement if you are still paying your mortgage.
1. Your income will be assessed differently
When a mortgage term extends past state pension age, standard residential lenders shift from assessing payslips or business accounts to evaluating verified post-retirement income.
Lenders will look at state pension projections, private pension drawdown schedules, annuity statements, or investment returns to confirm that post-retirement income comfortably covers monthly repayments.
2. Your loan term may be adjusted to fit lender age limits
Standard residential lenders maintain upper age limits, typically requiring loans to be cleared by age 70, 75, or 80. If you are remortgaging in your 50s or 60s, a lender may adjust your maximum allowable loan term to fit within these age limits.
While a compressed term pays off the mortgage faster, it increases monthly repayments, which must fit within your projected retirement budget.
3. You should avoid Standard Variable Rates (SVR)
Allowing a fixed deal to expire without taking action moves your balance onto your lender’s Standard Variable Rate (SVR). SVRs are typically higher than fixed or tracker rates, leading to an unnecessary increase in monthly costs.
Securing a new deal well before your current rate expires is key to keeping housing costs predictable.
How do you manage your mortgage renewal ahead of retirement?
Fraser-Tucker said carrying an extended mortgage term toward retirement was straightforward when managed proactively.
1. Overpay as much as possible
Most fixed-rate products permit up to 10% penalty-free overpayments each year.
Overpaying even modest amounts during higher-earning years directly reduces principal debt, naturally pulling a 35- or 40-year term back toward a traditional retirement horizon.
2. Consider a ‘product transfer’
transitioning to pension income can make full affordability re-assessment with a new lender complex. Therefore, an existing lender product transfer is an efficient route, said Fraser-Tucker.
Existing lenders often allow customers to switch to a new fixed rate without requiring a new income check or credit assessment.
3. Explore specialist later-life options
If standard age limits prevent a standard residential remortgage, specialist options such as Retirement Interest-Only (RIO) mortgages are designed specifically for retirees.
RIO mortgages allow you to service only the interest monthly, maintaining low, fixed outgoings while the loan capital is settled when the property is eventually sold.
4. Seek advice from a broker
Speak with an FCA-regulated mortgage broker up to six months before your current fixed rate ends. Pairing mortgage advice with an Independent Financial Adviser (IFA) ensures that any decision to use pension lump sums or drawdowns toward your mortgage is tax-efficient and aligned with your long-term estate plans.
The verdict on taking out a ‘marathon mortgage’
Fraser-Tucker said taking out a marathon mortgage is a practical solution to manage property costs today.
He added: “Extending your term does not mean you are locked into a 40-year commitment – by reviewing your mortgage at each fixed-rate renewal, utilising overpayment allowances where possible, and seeking expert advice early, you can keep your monthly payments manageable both now and into retirement.”